Last week a friend paid me back 4,300 won for a coffee. Not with coins, not with a crumpled bill pressed into my palm at the subway gate — she just held her phone over mine for a second, typed in my name, and it was done before I’d even finished saying “no rush.” That’s the moment that still gets me, three-plus years into living here. Back home, splitting a bill meant someone always ended up short, or you did the awkward Venmo request that sat unanswered for a week. In Korea, the money just arrives. Instantly. For four thousand won. This is Yijidaddy, and I want to talk about the cashless culture here — specifically KakaoPay, Toss, and the QR-code world that quietly runs underneath almost every transaction I make now.
You might assume a country famous for its late-night pojangmacha stalls and cash-only markets would still lean heavily on physical won. I certainly did, before I moved here. Turns out it’s almost the opposite. South Korea processes the majority of its card and mobile spending through non-physical methods now, and the market for mobile payments alone is valued in the tens of billions of dollars. I don’t say that to throw a stat at you — I say it because it matches exactly what I see every single day: I genuinely cannot remember the last time I paid for something under 20,000 won with paper cash. Even the tiny tteokbokki cart near my apartment, run by an ajumma who looks like she’s been doing this since before smartphones existed, has a laminated QR code taped to the side of her cart.
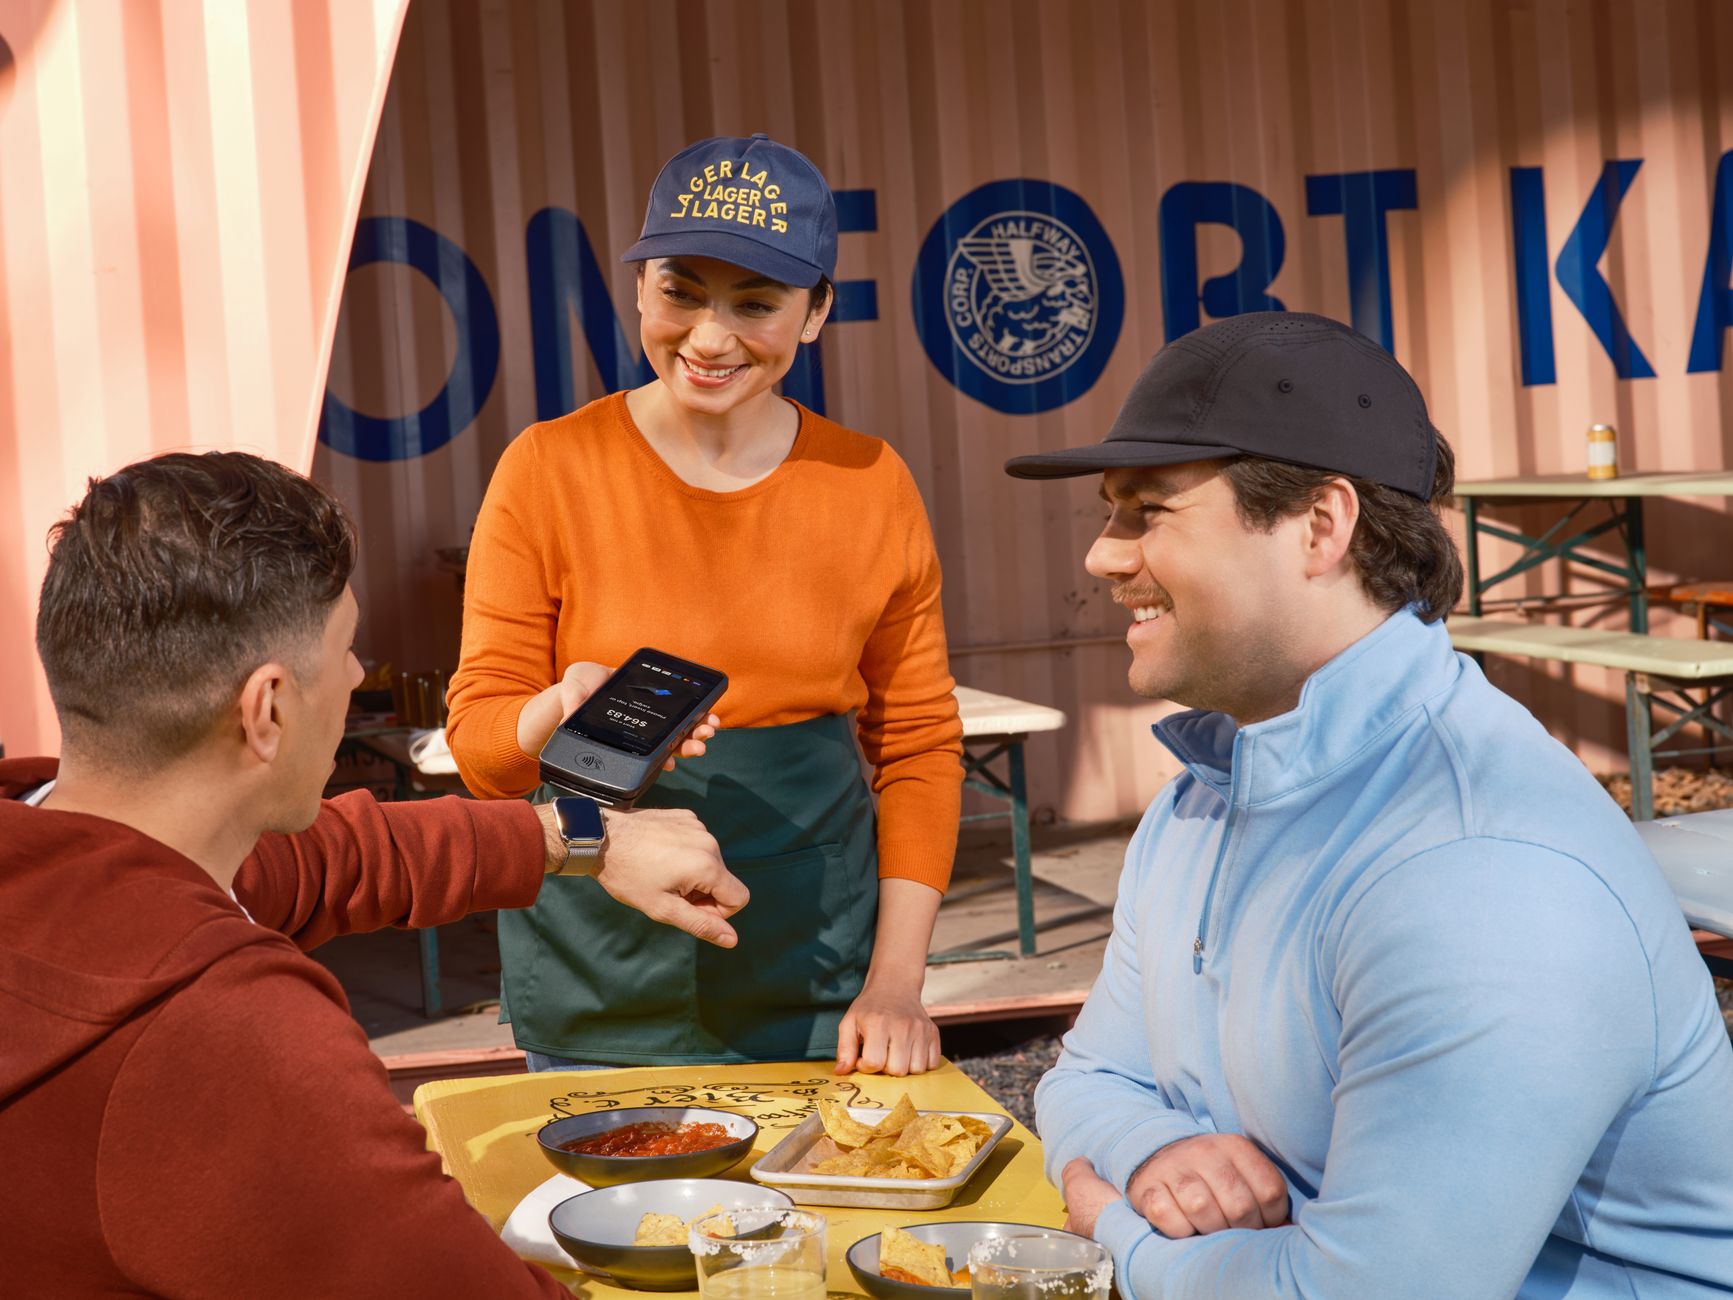
The apps that run the show
Two names dominate the conversation whenever payments come up: KakaoPay and Toss. KakaoPay lives inside KakaoTalk, which is basically the operating system of Korean social life — everyone I know, from my mother-in-law to my coworkers, has it open all day anyway, so folding payments into that same app was a genuinely smart move on Kakao’s part. You send money to a KakaoTalk friend the same way you’d send a message. Toss, on the other hand, started life more like a standalone finance app and has since ballooned into something closer to a full banking hub — transfers, savings, investing, even loan applications, all under one roof. Naver Pay exists too and gets real use, especially for online shopping, but in day-to-day in-person spending, it’s Kakao and Toss that I bump into constantly.
Here’s the part that surprised me most: Toss has basically become a verb. I’ve heard Korean coworkers say “그냥 토스해” — “just Toss me” — the exact way I’d hear an American say “just Venmo me.” Nobody says “transfer the money” anymore, not casually. A brand becoming a verb is a pretty specific marker of market saturation, and living here you feel that saturation constantly, in ways a market-share percentage on a slide never quite communicates.
QR codes are everywhere, and I mean everywhere
Sounds excessive, but I’ve paid for a 2,000-won bag of roasted chestnuts from a street cart using a QR code scan. I’ve paid my portion of a dinner bill by scanning a code taped to the table at a Korean barbecue place, my share pulled directly from my linked account before the side dishes were even cleared. Convenience stores, cafes, the guy who sells fish cakes near the station — the pattern repeats. You open the app, either you scan their code or they scan yours, and the transaction clears in a couple of seconds. No card swipe, no chip insert, no “please remove your card” beeping impatiently at you.

What threw me off at first was how casual the whole thing feels for something involving actual money changing hands. Back where I’m from, paying always had a small ceremony to it — hand over the card, wait, sign or tap, get the receipt. Here it’s closer to sending a text message. Oddly enough, that casualness is exactly what made me trust it eventually. When something works the same way every single time, a thousand times in a row, you stop bracing for it to fail.
Splitting bills without the awkward math
Group dinners in Korea used to make me anxious before I understood how this worked. Someone pays the full bill upfront — often just grabs the card and goes, no discussion — and then everyone else quietly Tosses or KakaoPays their share afterward, sometimes literally while still sitting at the table. There’s no calculator app, no arguing over who had the extra bottle of soju, no IOUs that quietly evaporate. You might expect that informality to lead to people forgetting or dodging payment, but in practice the social pressure of a visible, instant transfer keeps everyone honest. I’ve noticed the money usually shows up within minutes, sometimes before I’ve even sat back down from the bathroom.
This is different from how I handled group money before I lived here, where “I’ll pay you back” often meant “I will think about paying you back.” The friction is gone, and without that friction, the excuse disappears too.
Getting set up as a foreigner: the learning curve nobody warns you about
Here’s where things get less magical. Setting up KakaoPay or Toss as a foreigner isn’t quite the same one-tap experience Korean friends describe. You’ll generally need an Alien Registration Card, a Korean phone number on a local carrier, and — this is the part that trips people up — a Korean bank account already linked to your name. I’ve written separately about the actual bank account process itself (that deserves its own post, and if you’re at that stage, I go through what that was like for me here), so I won’t rehash the account-opening mechanics. What I’ll say specifically about the payment apps is this: once the bank account exists, linking it to Toss felt noticeably smoother than linking it to KakaoPay did for me. Toss has invested in an English interface that actually holds up through the identity verification steps, whereas KakaoPay’s foreigner-facing flow felt like it was translated as an afterthought — functional, but you’ll be squinting at a menu or two.
You might wonder whether it’s even worth the hassle if you’re just visiting rather than living here long-term. Turns out, no — tourists genuinely don’t need to go through any of this. If you’re just passing through, some KakaoPay QR terminals now accept scans from international wallet apps that support the Alipay+ network, so a short trip doesn’t require opening a Korean bank account at all. But for anyone actually settling in for work, study, or a visa longer than a few months, going through the ARC-plus-bank-account-plus-app pipeline eventually becomes worth it. Once it’s done, it’s done — you’re not redoing this every month.
Where T-money still fits into all this
If you’ve been reading long enough, you know I’ve already gone deep on how the T-money card actually works, so I won’t repeat that ground here. What’s worth noting briefly is how differently T-money and these payment apps sit in my daily habits. T-money is my subway-and-bus reflex — a physical tap that I don’t even think about anymore, partly because some transit gates still aren’t fully synced with app-based payment the way convenience store registers are. Meanwhile KakaoPay and Toss are what I reach for basically everywhere else: shops, restaurants, paying friends back, online orders. They overlap a little — you can link T-money inside some of these apps now — but in practice I still carry the physical card out of habit, even though my phone could probably replace it entirely at this point.
The part that still catches me off guard
Even now, there’s a small moment of surprise every time a transaction clears in under two seconds. I’ve noticed I still instinctively reach for my wallet before catching myself and pulling out my phone instead — old habits from a cash-and-card upbringing don’t disappear overnight. What’s changed is the anxiety around it. Early on, I worried constantly about whether a payment actually went through, whether I’d fat-fingered an amount, whether the QR code was even legitimate. These days I trust the system the way I trust a subway door to open when the train stops — not because I understand every mechanism behind it, but because it has simply never once let me down in three years of daily use.
That trust, more than any statistic about market size, is probably the real story of cashless Korea. It’s not that the technology is flashy — a QR code is about as unglamorous as tech gets. It’s that it works quietly, constantly, in the background of ordinary life, until one day you realize you haven’t touched a coin in months and didn’t even notice.
FAQ
Can foreigners use Toss or KakaoPay without a Korean ID?
Not for the full local account experience — both apps require an Alien Registration Card, a Korean phone number, and typically a linked Korean bank account before you can send or receive money, or scan to pay at most local stores. Short-term visitors without an ARC generally can’t sign up for the full version of either app, though this doesn’t mean you’re locked out of every payment option while visiting, since some tourist-facing QR terminals accept scans from compatible international wallet apps instead.
Do I need both KakaoPay and Toss, or is one enough?
You can get by with just one, but I’ve noticed most long-term expats end up with both eventually, simply because different friends and merchants default to different apps. KakaoPay tends to win for in-person QR payments at small shops and stalls, while Toss gets used more for quick person-to-person transfers and banking-style features. If you had to pick just one to start with, I’d lean toward whichever one your closest Korean friends or coworkers already use, since half the value is being able to send and receive money with the people around you.
What happens if my phone dies or I have no signal — is cash still accepted everywhere?
Yes, cash is still legal tender everywhere and small businesses in particular will always take it. I’ve never been refused a cash payment in Korea. That said, I’ve noticed I carry less and less physical cash simply because I rarely need it, so a dead phone battery on a day I was relying entirely on app payments has genuinely left me stuck once or twice — a small reminder to keep at least a little cash tucked away as a backup, even in a place this thoroughly cashless.
Leave a Reply